Rate buydown or price cut? What saves buyers more?

Rate buydown or price cut? What saves buyers more in Prince George's County
The housing market in Prince George's County has shifted, and the negotiating power is moving from sellers to buyers.
Across the DC area in August, there were 11% more homes for sale than a year ago, according to Bright MLS. Showings were down 7%, and 12% fewer homes went under contract. Here in Prince George's County, home values have dipped over the past year.
For buyers, that means more homes to choose from and less competition for them.
Why are so many buyers waiting?
Rates are a big part of it. Freddie Mac's average 30-year rate was 6.76% in early September, up from 6.35% a year ago. Bright MLS chief economist Lisa Sturtevant says some homebuyers are hitting an "affordability ceiling."
A lot of buyers have decided to sit on the sidelines until rates come down. In the meantime, there are real ways to keep your costs down.
What can buyers negotiate right now?
With more homes on the market and fewer buyers competing, sellers are more open to negotiating. On the right property, buyers can ask for:
- help with closing costs
- repairs on the home
- the seller paying the buyer agent commission
- an extended settlement date
- little perks, like the seller including personal property in the sale
The most room is usually on homes that were overpriced and have already been through price reductions and time on the market.
Seller money can also go toward your interest rate. That's called a rate buydown, and it can do more for your monthly payment than a lower price.
What is a rate buydown?
A rate buydown means paying money up front for a lower interest rate. When a seller credit covers that cost, the lower rate is paid for with the seller's money.
There are two kinds:
- A temporary buydown lowers your rate for the first 2 or 3 years. After that, you pay the full rate.
- A permanent buydown uses discount points to lower your rate for the life of the loan.
The options vary by lender, and the right choice depends on your budget and how long you plan to keep the loan.
Price cut, closing cost help or buydown: which saves more?
Take a $450,000 home in Prince George's County bought with a 30-year fixed FHA loan at 6.76% (7.51% APR). The buyer needs about 6.5% of the price to close:
- $15,750, or 3.5%, for the down payment
- $13,500, or about 3%, for closing costs, prepaids and escrows
The seller agrees to give $13,500, which is 3% of the price. There are three ways a buyer could use it.
Option 1: Closing cost help. The seller's $13,500 covers your closing costs, prepaids and escrows, so you only bring the down payment.
Option 2: Price cut. The seller takes $13,500 off the price instead, and you buy the home for $436,500. Your loan is smaller, but you pay all of your closing costs yourself.
Option 3: Rate buydown. $9,000 of the credit buys your rate down from 6.76% to 6.26% (7.21% APR) for the life of the loan. The other $4,500 goes toward your closing costs, and you pay the rest.
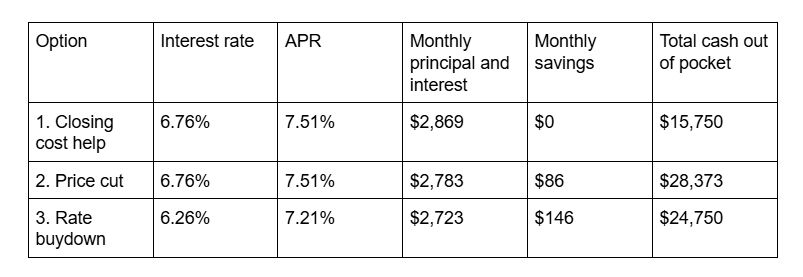
Payments show principal and interest only on a 30-year fixed loan. Taxes, homeowners insurance and FHA mortgage insurance will make the actual monthly payment higher.
Is a rate buydown worth it?
In this example, the buydown has the lowest payment. It saves $146 a month compared with option 1 and takes $9,000 more cash at settlement. At $146 a month, you make that $9,000 back in about 62 months, a little over 5 years.
A price cut sounds like the obvious thing to ask for. Here, it saves $86 a month, takes about $12,600 more cash than option 1 and needs about 12 years to break even. The buydown beats it on both counts, with a lower payment and less cash at settlement.
A permanent buydown works best if you plan to keep the loan past the break-even point. If you expect to sell or refinance within 5 years, closing cost help may serve you better. With a temporary buydown, make sure the full payment fits your budget before the lower rate ends.
Run the numbers before you make an offer
After helping hundreds of homeowners in the DMV over the last 24 years, I've learned that the best deal is the one that fits your numbers. I'm both a Realtor and a licensed loan officer, so I can show you what each option does to your payment and your cash at settlement.
Call or text our office at 240-255-9027 and we'll set up a brief 15 minute call with me or another member of The Heyward Homes Team. We'll look at the homes you're considering and show you which option saves you the most.
This is an example only, based on a 30-year fixed FHA loan with 3.5% down on a $450,000 purchase, with closing costs, prepaids and escrows estimated at 3% of the price. The loan amount includes FHA's 1.75% upfront mortgage insurance premium. APRs assume lender fees of 0.25% of the loan amount, 1 day of prepaid interest, and FHA annual mortgage insurance of 0.55% for the life of the loan. The 7.21% APR also includes $9,000 in discount points. Rates, points and costs vary by lender and borrower. This is not a commitment to lend.
Charles C. Heyward, Jr., Associate Broker
The Heyward Homes Team of Samson Properties
Mortgage Loan Originator - NMLS #2568268
1st Step Financial Services, Inc. - NMLS #204295
Equal Housing Lender
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "